
Storm damage tree removal
Storm work is different work. The wood is under load, the tree is where physics put it rather than where anyone planned, and the worst damage is often the piece still hanging. We clear what is down, make safe what is not, and leave you a paper trail your insurer will accept. If something is on the house right now, treat it as an emergency and call.
The three shapes storm damage takes
Hung-up limbs are the ones that broke but did not land: caught in the crown, resting on a roof edge, snagged on a lower branch. Tree workers call them widow-makers for a reason. A hung limb can sit quietly for a week and then come down in the next breath of wind, and it is the one kind of storm damage you should never put a ladder against. We bring them down on rope, in pieces, from above.
Split forks happen where two stems meet in a tight V. The wind levers them apart and the crack runs down into the trunk. Some splits mean the whole tree comes down; a surprising number can be saved instead with a brace and cable if the split is caught early, which is one more reason to have someone look quickly rather than in a month.
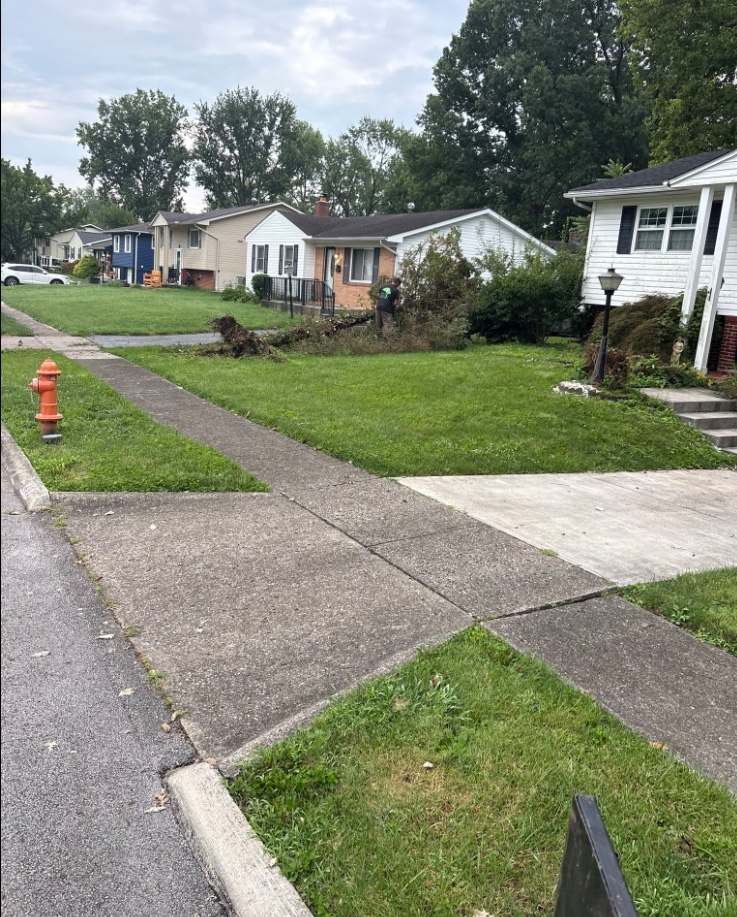
Uprooted trees lift a plate of roots and lawn as they go over. If the tree is fully down, the danger is mostly past and the job is a careful cut-up: the trunk is under tension and the root plate can slam back upright when the weight of the stem is cut away, so the order of cuts matters more than the size of the saw. A tree leaning with its roots half lifted is the opposite: that one is still falling, just slowly, and it goes to the top of our list.
What insurance pays for, and what it does not
Homeowner’s policies generally pay when a tree damages a covered structure: the house, the garage, a fence, sometimes a shed. The tree’s removal off that structure and the repair both fall under the claim, minus your deductible. What is generally not covered is a tree that falls and hits nothing: a trunk across the lawn is your cost, however big it is, and so is taking down a damaged tree that is still standing. Debris hauling on a covered claim is usually capped at a few hundred dollars too, so keep the clearing and the hauling as separate lines. Before anything is cut, photograph everything from several angles; insurers pay on the damage they can see. We give you an itemized written invoice that separates the off-the-structure work from the rest, because that is the split your adjuster needs.
How a storm call runs
- Make it safe before making it tidy Hung limbs and half-lifted trees first, cleanup second. Nothing else happens under a widow-maker.
- Photograph before we cut If a structure is hit, the pictures come first: wide shots, close-ups, the point of contact. Cut first and the claim gets harder.
- Lift the weight off the structure Sections come off the roof or fence on rope or with the lift, smallest loads first, so nothing rolls or drags on the way down.
- Cut up what is on the ground Tension and compression are read before each cut. This is the part of tree work that hurts amateurs, and it is not a chainsaw-rental job.
- Clear, stack or haul, and write it up Brush chipped, wood stacked or hauled as you choose, and an itemized invoice that holds up in front of an adjuster.
After the wind, around Reynoldsburg


What people ask after a storm
The tree is on my roof. Do I call you or the insurer first?
Call us, photograph everything while you wait, then open the claim. Getting the weight off the structure quickly limits the damage, which the insurer wants as much as you do, and the claim runs on the photos rather than on who was called first. If it is on the house right now, use the emergency line.
A big limb fell but hit nothing. Will insurance pay to clear it?
Almost certainly not. A tree or limb that falls without damaging a covered structure is the owner’s cost. It is worth a call to your agent to confirm your policy, but plan on paying for that one yourself.
My neighbor’s tree fell on my garage. Whose insurance is it?
Yours, usually. The claim goes to the policy covering the damaged property, not to whoever owned the tree. The neighbor’s side only enters into it if their tree was known to be dead or dangerous and they had been told, which is where photographs and dated letters earn their keep.
There is a broken limb caught in the crown. Can it wait?
Treat it as no. A hung limb is stored energy over whatever is underneath it, and wind, rain weight or rot decide when it releases, not you. Keep people and cars out from under it and have it brought down on rope soon.
The tree went over and lifted its roots, but it is caught on another tree. Now what?
That is the most dangerous configuration on this page: a partially failed tree under load against a live one. Nothing about it is a homeowner job. Keep everyone clear of the line it would take to the ground and call.
How fast can you get to me after a big storm?
We order the list by danger: structures and hung wood first, blocked driveways next, lawn cleanup last. We will tell you honestly where you sit and when to expect us, which after a front like August 2026 matters more than a cheerful promise.
Other things we do
Where we work
Down, hanging, or leaning: call before you cut
Storm wood is loaded wood. Send us a photo if you can, keep everyone out from under it, and we will tell you on the phone how urgent it really is.